The best credit card is the one that matches how you spend and whether you pay in full each month. Chase Freedom Unlimited and Capital One Quicksilver are simple cash back cards with no annual fee, Discover it Cash Back rewards you for tracking rotating 5% categories, and Chase Sapphire Preferred, Capital One Venture and the Amex Gold suit travelers and big restaurant and grocery spenders who will use the points. If you carry a balance, the intro APR and regular APR matter far more than any reward.
This guide is for you if you want one good everyday card, or a second card that earns more on the things you already buy. We picked six cards that cover the main choices: flat-rate cash back, rotating categories, and travel or dining points.
The deciding question is whether you pay your balance in full. If you do not, interest will cost more than any card earns back, so the intro APR and regular APR come first. If you do, compare rewards rates against your actual spending, and count only the credits you would use anyway when weighing an annual fee.
Below you will find each card's fees, rewards and APRs, a side-by-side table of costs, how cash back compares with travel points, the fine print to check, and options if your credit is still building.
Company reviews
- Annual fee
- $0
- Rewards rate
- 1.5%
- Intro offer
- $200
Why we picked it. It combines a solid base rate on everything with bonus categories most people already spend in, plus a 15-month 0% APR window. With no annual fee, every dollar you earn is pure upside.
More details, pros and cons
Pros
- No annual fee
- Earns at least 1.5% on every purchase
- 0% intro APR covers balance transfers too
- Bonus needs only $500 in spending
Cons
- 5% travel rate applies only through Chase Travel
- No bonus if you received one for this card in the past 24 months
- Balance transfers carry a fee
Skip it if: You want travel perks such as transfer partners or no foreign transaction fees.
More about Chase Freedom Unlimited
A versatile cash back card offering a baseline 1.5% cash back on all purchases, supplemented by highly valuable bonus categories for dining, drugstores, and travel.
- Annual fee
- $95
- Rewards rate
- 5x on Chase Travel, 3x on dining
Intro offer: 75,000 points after $5,000 in purchases in the first 3 months
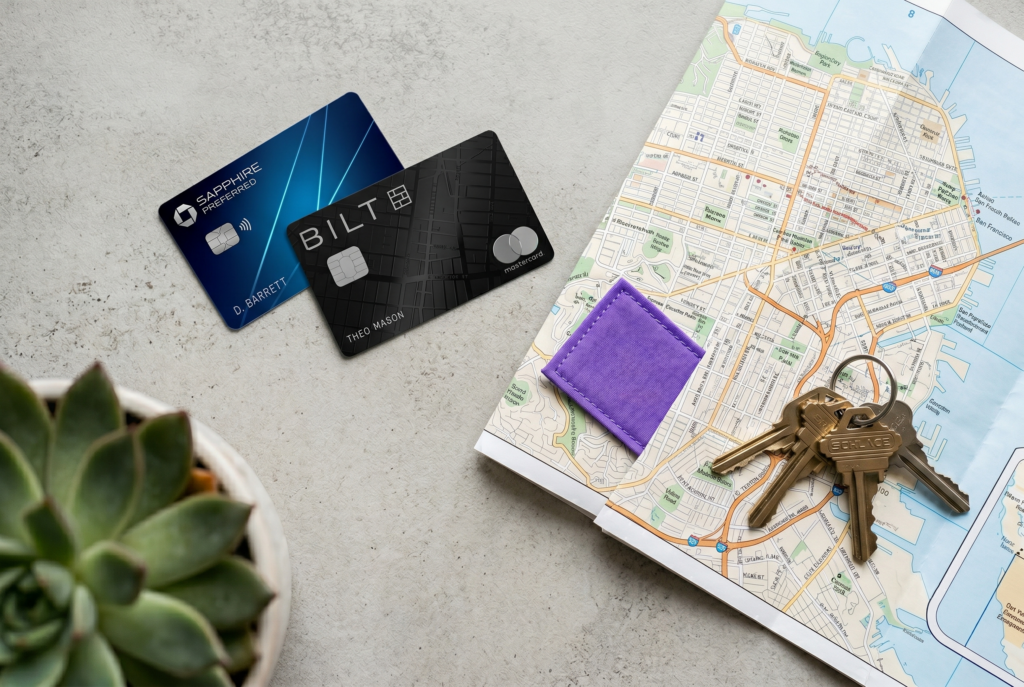
Why we picked it. It earns 3x in several everyday categories and 5x on Chase Travel for a modest fee. It is the natural step up if you are ready to earn travel points without paying for a premium card.
More details, pros and cons
Pros
- Strong 3x categories, including dining and gas
- Large 75,000-point bonus
- Limited-time 5x on Lyft and select Peloton purchases through 2027
Cons
- Bonus requires $5,000 in spending in 3 months
- No intro APR offer
- Bonus may be unavailable if you held this card before
Skip it if: You will not spend $5,000 in three months, or you carry a balance.
More about Chase Sapphire Preferred
A mid-tier travel rewards card earning 5x on Chase Travel and 3x on dining, with flexible points transferable to 13+ airline and hotel partners. Ideal for frequent travelers.
- Annual fee
- $0
- Rewards rate
- 5%
- Intro offer
- Cashback Match: all cash back earned in year one is matched
Why we picked it. The first-year Cashback Match effectively doubles everything you earn, and the regular APR range is the lowest among our picks. Discover is now part of Capital One, which counts Discover card accounts as Capital One accounts.
More details, pros and cons
Pros
- No cap on the first-year Cashback Match
- Lowest regular APR range of our picks
- 15 months of 0% APR
- No annual fee
Cons
- 5% categories must be activated each quarter and have a spending cap
- Only 1% outside the bonus categories
- Balance transfer fee applies
Skip it if: You want a set-and-forget card and will not track quarterly categories.
More about Discover it® Cash Back
A popular cash back card offering 5% back on rotating quarterly categories and an unlimited dollar-for-dollar match of all cash back earned in the first year.
Show all 5 picks2 more, ranked 4 to 5
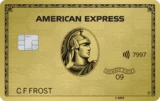
Best for heavy restaurant and U.S. supermarket spending: Amex Gold
- Annual fee
- $325
- Intro offer
- Varies by applicant
Rewards rate: 4X at restaurants worldwide (up to $50,000 a year) and U.S. supermarkets (up to $25,000 a year), 3X on flights booked directly with airlines or through AmexTravel, 1X other
Why we picked it. If you spend a lot on dining out and groceries, 4X points in both categories adds up fast. The monthly credits can offset much of the $325 fee, but only if you already use those merchants.
More details, pros and cons
Statement credits: Up to $120 dining credit, $120 Uber Cash, $100 Resy credit per year, plus a Dunkin' credit
Pros
- Credits for dining, Uber, Resy and Dunkin'
- Membership Rewards points can transfer to travel partners
- Up to 5 additional cards with no annual fee
Cons
- Highest annual fee of our picks
- Credits are paid monthly and expire if unused
- Welcome offer is not guaranteed and varies by applicant
Skip it if: You will not use the monthly credits, or you spend little on dining and groceries.
More about Amex Gold
A premium dining and grocery card earning 4x points at restaurants worldwide and U.S. supermarkets, plus over $400 in annual statement credits. Best for food-focused, high-volume spenders.
- Annual fee
- $95
- Rewards rate
- Unlimited 2X miles on every purchase, 5X on hotels
- Intro offer
- 75,000 miles after $4,000 in purchases in 3 months
Why we picked it. Venture keeps travel rewards simple: 2X on everything, miles that do not expire for the life of the account, and transfers to 15+ loyalty programs. The Global Entry or PreCheck credit can cover a big share of the fee once every few years.
More details, pros and cons
Travel perks: No foreign transaction fees; up to $120 credit for Global Entry or TSA PreCheck
Pros
- No bonus categories to track
- No foreign transaction fees
- Up to $120 Global Entry or TSA PreCheck credit
- Miles transfer to 15+ travel programs
Cons
- $95 annual fee
- No intro APR
- Best value depends on travel bookings or transfers
Skip it if: You rarely travel and would rather have cash back with no fee.
More about Capital One Venture
A mid-tier travel card earning a flat 2x miles on every purchase plus a $120 Global Entry or TSA PreCheck credit. Best for simple, consistent travel rewards.
What a credit card costs
A card’s cost comes from three places: the annual fee, interest if you carry a balance, and fees such as balance transfer and foreign transaction fees. Among our picks, annual fees run from $0 (Freedom Unlimited, Discover it, Quicksilver) to $325 (Amex Gold), as listed October 2026.
Interest usually outweighs rewards. On a card with a 20% APR, a balance you carry for a year costs far more than the 1.5% to 4% you earn back. If you will carry a balance, pick for the intro APR and the lowest regular APR first, and rewards second.
| Card |
Annual fee |
Regular APR (variable) |
| Discover it Cash Back |
$0 |
17.74% to 26.74% |
| Chase Freedom Unlimited |
$0 |
18.49% to 27.99% |
| Capital One Quicksilver |
$0 |
18.74% to 28.74% |
| Chase Sapphire Preferred |
$95 |
19.49% to 27.74% |
| Capital One Venture |
$95 |
19.74% to 28.74% |
| Amex Gold |
$325 |
19.74% to 28.74% (Pay Over Time) |
Rates as listed on each issuer’s site in October 2026. Your APR depends on your credit.
How to choose the right credit card
- Decide if you will pay in full. If not, prioritize a 0% intro APR and a low regular APR.
- Look at your last three months of spending. Big dining and grocery totals favor the Amex Gold, frequent travel favors Sapphire Preferred or Venture, and spending spread across many categories favors a flat-rate card.
- Do the annual fee math. Count only credits and perks for things you already pay for today.
- Check the bonus requirement. Apply only if you can reach the spending threshold with normal purchases.
- Read the issuer’s rules on repeat bonuses. Chase lists a 24-month rule for Freedom Unlimited; Capital One lists 48 months for Quicksilver.
Cash back vs. travel rewards
Cash back (Freedom Unlimited, Discover it, Quicksilver) is simple: you know what each purchase is worth. Travel points and miles (Sapphire Preferred, Venture, Amex Gold) can be worth more when you book travel or transfer to airline and hotel partners, but their value depends on how you redeem them.
A practical rule: if you take fewer than one or two paid trips a year, a no-fee cash back card is usually the better deal. If you travel often and will learn the redemption options, a $95 travel card can return more than its fee.
Red flags and fine print to check
- Changing welcome offers. Welcome offers change often and can vary by applicant, as the Amex Gold page shows.
- Balance transfer fees. A 0% intro APR on transfers usually still comes with a transfer fee.
- Caps on bonus categories. Discover’s 5% has a quarterly maximum; Amex Gold’s 4X has annual caps.
- Credits that require enrollment or specific merchants. Monthly credits you forget to use are lost.
- Rates and fees tables. Always open the issuer’s official pricing and terms before you apply. The CFPB also keeps a public database of credit card agreements.
If you are building or rebuilding credit
Our picks generally require good to excellent credit. If you are new to credit or rebuilding, start with a secured card or a student card, keep your balance low and pay on time for six to twelve months, then apply for a rewards card. Capital One and Discover both let you check eligibility before you apply, which helps you avoid a hard inquiry on a card you are unlikely to get.
Terms to know
- APR
- Annual percentage rate: the yearly cost of borrowing on a card, which issuers must disclose before you agree.
- Variable APR
- An APR that moves with a benchmark rate, so your interest rate can change over time.
- Intro APR
- A temporary lower rate, often 0%, for a set number of months after you open the card.
- Balance transfer
- Moving a balance from one card to another, usually for a fee.
- Foreign transaction fee
- A fee some cards charge on purchases processed outside the United States.
- Transfer partner
- An airline or hotel program that accepts points or miles from a card's rewards program.