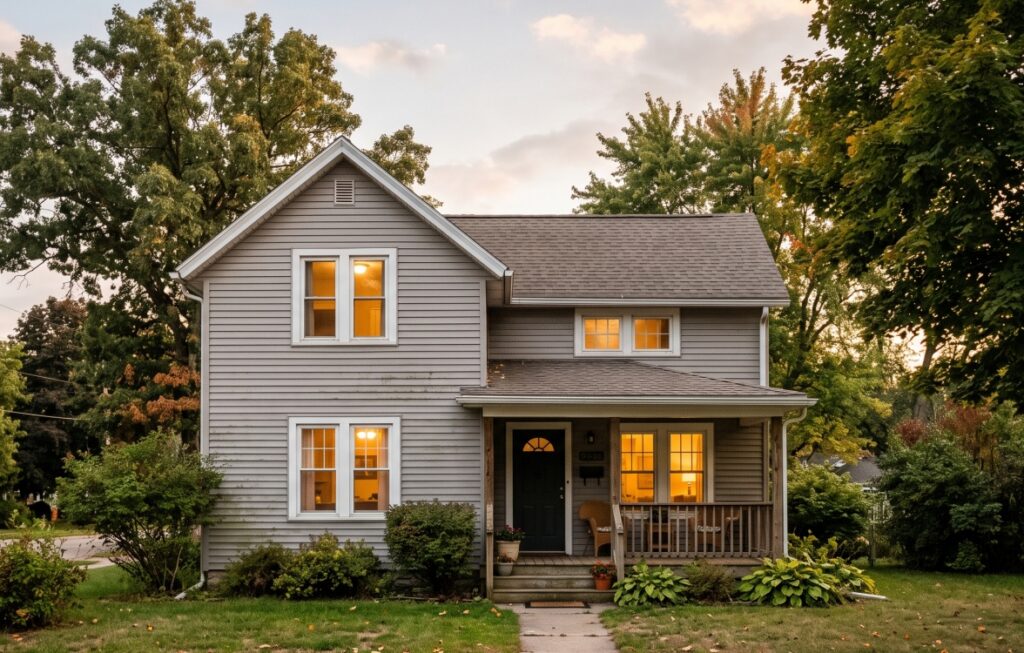
The best home insurance companies pair top financial strength with easy claims and good bundling discounts. Travelers and USAA carry AM Best's highest rating, A++, State Farm and Allstate are rated A+, and GEICO sells home policies from partner carriers through its own agency. Get quotes from at least three insurers, insure to full replacement cost, and remember that price and availability vary by state, home and claims history.
This guide is for homeowners buying a first policy, switching after a big renewal increase, or checking whether their current insurer still makes sense. None of the companies here publish a national price, so the goal is a short list worth quoting, not a cheapest-company ranking.
Three things matter most. Financial strength comes first, because a policy is only as good as the company's ability to pay a large claim. Next is who actually handles your claim, which is not always the brand on the ad. Then comes the dwelling limit: it should match what it would cost to rebuild your home, not its market value.
Below you will find insurers compared on ratings, buying options, discounts and availability, followed by what a policy covers and excludes, how prices and rules change by state, and the warning signs in a cheap quote.
Company reviews
Best for optional add-ons and local agent support: Allstate
- AM Best rating
- A+, affirmed August 2025
- How you buy
- Local agents, online or by phone
- Notable discount
- Home and auto bundle discount in many states
Why we picked it. Allstate combines an A+ financial strength rating with a large agent network and a long list of optional coverages, including protection if you rent out your home. Its site also shows what a typical policy covers in your state.
More details, pros and cons
Optional coverage: Flood insurance access, HostAdvantage for home sharing, personal umbrella
Pros
- Many add-ons, including home sharing coverage
- Local agents can review your coverage and discounts
- Access to flood insurance and personal umbrella policies
Cons
- Not available in every state
- Discounts and savings vary by state and product
- No published prices, so you must request a quote
Top Bundling Discounts
Skip it if: Allstate does not write new home policies in your state, or you want a purely online experience.
More about Allstate
Allstate stands out as a top national carrier offering broad availability and excellent multi-policy bundling options. With a superior financial rating and optional coverages like green improvement reimbursement, it provides robust protection for homeowners looking for stability and comprehensive discounts.
Best for GEICO auto customers who want one place to shop home coverage: GEICO
- AM Best rating
- Depends on the partner carrier that writes your policy
- How you buy
- GEICO Insurance Agency shops a network of partner carriers
- Notable discount
- Bundling with GEICO auto may help lower your premium
Why we picked it. GEICO does not underwrite most home policies itself. Its agency compares partner carriers for you and lets you manage home coverage alongside your GEICO auto policy, which saves calls if you already insure your car there.
More details, pros and cons
Pros
- One agency compares several carriers
- Manage home and auto in one place
- Clear explainers on replacement cost and the 80% rule
Cons
- Your policy, claims and rating come from a partner carrier, not GEICO
- Service quality depends on which carrier you are placed with
- Discounts depend on the partner carrier
Wide Carrier Network
Skip it if: You want your home claim handled by the same company that insures your car.
More about GEICO
Geico operates as an extensive agency network, partnering with multiple third-party underwriters to provide coverage across all states. This model allows users to easily compare rates and secure significant bundling discounts with their existing Geico auto policies.

Best for bundling home and auto through a local agent: State Farm
- AM Best rating
- A+ for State Farm Fire and Casualty
- How you buy
- Local agents or online quote
- Notable discount
- Bundle home and auto and save up to $1,429
Why we picked it. State Farm advertises the largest bundle savings figure of the insurers we compared, and its agent model suits you if you want one person handling your home, auto and life policies. AM Best cut its rating from A++ to A+ in November 2025, which is still Superior, and it is not writing new home policies in California and some other states.
More details, pros and cons
Pros
- A+ (Superior) financial strength
- Largest advertised bundle savings among our picks
- Discounts for security devices, roofing and a claim-free history
Cons
- Not writing new home policies in California, Massachusetts or Rhode Island
- Bundle savings figure is based on savings reported by new policyholders
- Flood coverage requires a separate policy
- No published prices, and quotes vary widely by state
19,000+ Local Agents
Skip it if: You want only a home policy with no auto bundle, since much of its pitch rests on multi-policy savings.
More about State Farm
State Farm is the largest property insurer in the nation, boasting an unparalleled network of local agents. It combines highly competitive premium rates with personalized, face-to-face service, making it a top choice for those who value traditional customer support and strong financial backing.
Show all 5 picks2 more, ranked 4 to 5
Best for discounts on smart home and protective devices: Travelers
- AM Best rating
- A++ for the Travelers Reinsurance Pool
- How you buy
- Independent agents
- Notable discount
- Early quote discount up to 10%
Why we picked it. Travelers publishes its ratings from all four major agencies, and its main pool carries AM Best's highest grade. It rewards you for planning ahead (up to 10% off for quoting early) and for homes with sprinklers, alarms and connected leak or fire sensors.
More details, pros and cons
Pros
- Top ratings from AM Best, S&P, Moody's and Fitch
- Sold through independent agents who can compare options
- Discounts for multiple policies and a loss-free history
Cons
- Florida subsidiary First Floridian is rated A-, lower than the main pool
- Some add-on lines (flood, motorcycle) come from partners through InsuraMatch
- No published prices
Top Financial Strength
Skip it if: You live in Florida and want the A++ rated entity, since Florida policies may sit with a lower-rated subsidiary.
More about Travelers
Travelers brings decades of industry experience and an exceptional financial strength rating to its policyholders. With valuable add-ons like guaranteed replacement cost and multi-policy discounts, it is a highly stable choice for homeowners seeking customized dwelling protection.
Best for military members, veterans and their families: USAA
- AM Best rating
- A++, affirmed July 2025
- How you buy
- Directly from USAA
Why we picked it. USAA has AM Best's top financial strength rating and its highest long-term credit rating. If your family is eligible, it is often the first quote to get, especially if you bundle with USAA auto.
More details, pros and cons
Pros
- aaa long-term credit rating from AM Best
- Home, auto and banking under one membership
- Direct service without agents
Cons
- Available only to eligible members
- No local agent offices
- We could not load its discount details to confirm them
Best Military Value
Skip it if: You have no military connection, since you will not be eligible.
More about USAA
USAA provides unparalleled insurance value tailored specifically for active military, veterans, and their families. With exceptionally low average rates, standard replacement cost coverage, and deployment-specific benefits, it represents the gold standard for eligible policyholders.
What home insurance costs and what drives the price
None of these insurers publish a national price, because premiums depend on your address and your home. The biggest factors are:
- Replacement cost. What it would cost to rebuild your home, based on size, materials and local labor.
- Location. Wildfire, hurricane, hail and crime risk, plus distance to a fire station.
- Roof age and material. Older roofs raise premiums and can limit coverage.
- Claims history and credit-based insurance score. Insurers use both where your state allows it.
- Deductible. A higher deductible lowers the premium but raises what you pay after a loss.
The quickest ways to lower your cost are to bundle with auto, add protective devices and raise your deductible to an amount you could pay from savings.
What homeowners insurance covers and excludes
| Coverage |
What it pays for |
| Dwelling |
Repairing or rebuilding the house |
| Other structures |
Detached garage, fence, shed |
| Personal property |
Furniture, clothing, electronics |
| Loss of use |
Hotel and living costs if the home is unlivable after a covered loss |
| Personal liability |
Injuries or damage you cause to others, including legal defense |
Common exclusions: flood, earthquake, maintenance problems, and wear and tear. FloodSmart notes that most homeowners policies do not cover flood damage, so you would buy that through the National Flood Insurance Program or a private flood insurer.
How to choose a home insurance company
- Check financial strength. An AM Best rating of A or higher signals the insurer can pay claims. Confirm the rating applies to the company that will write your policy.
- Know who handles claims. With agency models like GEICO’s, a partner carrier pays your claim.
- Insure to replacement cost. Ask for dwelling coverage equal to the full cost to rebuild, not market value.
- Compare at least three quotes with the same coverage limits and deductibles.
- Ask about discounts for bundling, protective devices, a new roof, a claim-free history and early purchase.
- Check complaints on your state insurance department’s site.
Replacement cost vs. actual cash value
Replacement cost pays to rebuild or replace with new items of similar kind and quality. Actual cash value subtracts depreciation, so an older roof or sofa pays out far less.
Many insurers also expect you to insure the home for at least 80% of its replacement cost. If you carry less, a claim may be paid only in proportion, as GEICO’s guide explains. Review your dwelling limit after renovations or when local building costs rise.
How home insurance varies by state
Home insurance is regulated state by state, so the best company where you live may differ from a national ranking.
- Availability. Allstate notes it is not available in every state, and Travelers ties coverage and discounts to state availability.
- Ratings by subsidiary. Travelers’ Florida subsidiary is rated A-, while its main pool is A++.
- Catastrophe deductibles. Coastal and hail-prone states often use separate percentage deductibles for wind or hail.
- Rules on pricing factors. Some states limit the use of credit-based scores.
If you struggle to find coverage, ask an independent agent or look into your state’s FAIR plan, the insurer of last resort in many states.
Red flags when you shop
- A quote far below the others, which often means lower limits, actual cash value roof coverage or a high wind deductible.
- Dwelling coverage set to market value or purchase price instead of rebuild cost.
- An unfamiliar carrier with no AM Best rating.
- Pressure to sign the same day, or a request to pay by gift card or crypto.
Terms to know
- Dwelling coverage
- The part of a policy that pays to repair or rebuild the house itself.
- Replacement cost
- Payment to repair or replace property with new materials of similar quality, without subtracting depreciation.
- Actual cash value
- Replacement cost minus depreciation, which means older items pay out less.
- Deductible
- The amount you pay toward a covered claim before insurance pays.
- AM Best rating
- An independent grade of an insurer's financial ability to pay claims, from A++ (Superior) down.
- Loss of use
- Coverage for extra living costs when a covered loss makes your home unlivable.
- FAIR plan
- A state-backed insurer of last resort for homes that cannot get coverage in the regular market.